
Investment Weekly: Profits power ahead
9 November 2026
Key takeaways
-
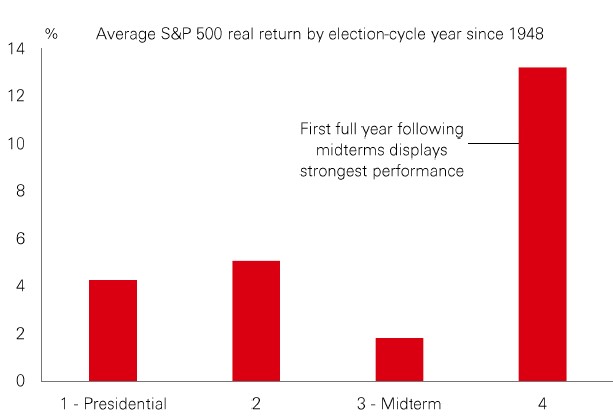
A "blue wave" has swept Washington, with Democrats flipping both Houses of Congress. Historically, the year following midterms is the strongest of the presidential cycle for US stocks. In theory, passing the vote lifts election uncertainty, and when the result produces divided government, the gridlock further reduces policy risk by blocking major legislative shifts.
-
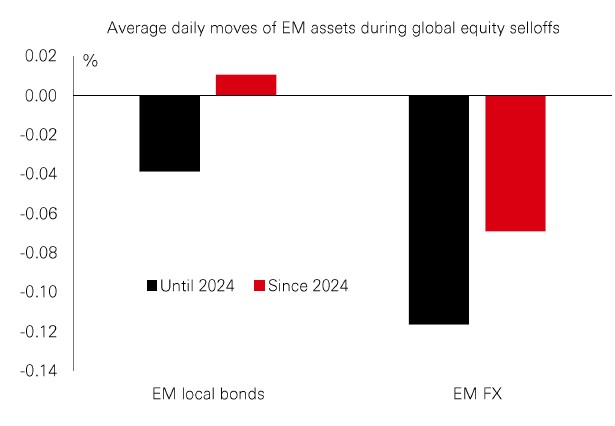
An old adage holds that when global markets sneeze, emerging markets (EM) catch a cold. Since mid-August, they have faced a barrage of shocks: elevated oil prices amid Middle East tensions, an AI-led global equity sell-off, and a hawkish repricing of US interest rates.
-
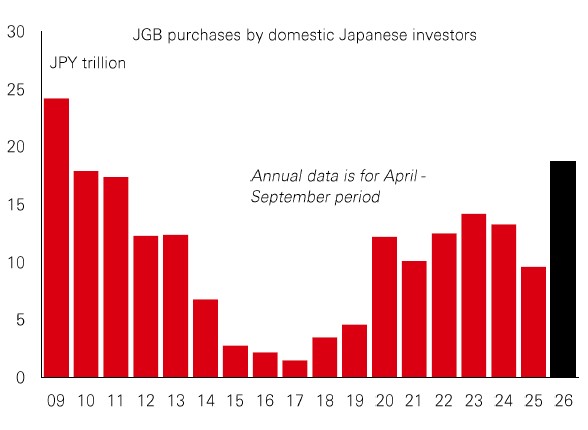
After years chasing returns abroad, Japanese capital is flocking back to native shores. With domestic yields at multi-decade highs, local institutions are stepping in to absorb supply, offering a counterweight as the Bank of Japan shrinks its bond portfolio.
Chart of the week – Profits power ahead
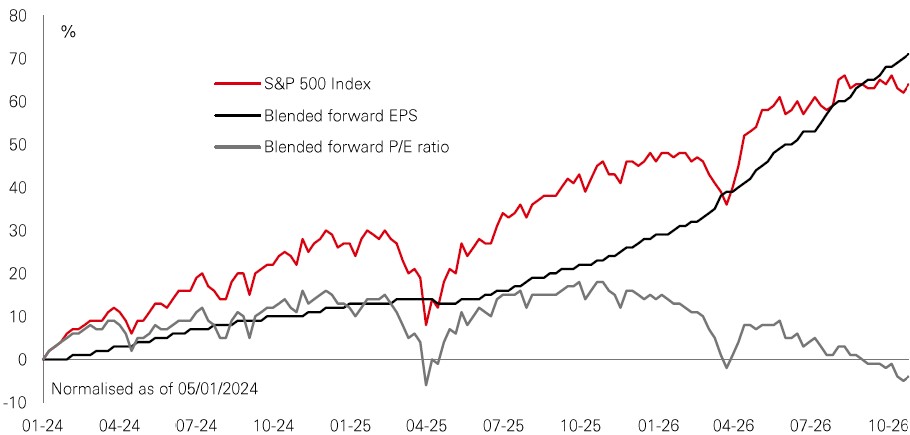
Global equities have demonstrated remarkable resilience this year, holding near record highs despite a barrage of macroeconomic headwinds. Markets have had to contend with surging oil prices, 10-year US Treasury yields exceeding 5%, renewed Fed rate hikes, and growing scrutiny over the durability of the AI boom.
Part of this resilience reflects powerful buffers within the broader macro system. More activist fiscal and industrial policy, cushioned energy reserves, market flexibility and rapid private-sector supply-chain adaptation have enabled economies to absorb external shocks that might previously have triggered a downturn.
At the market level, booming corporate profits have done the heavy lifting. The Q3 reporting season has underscored this fundamental strength, with the S&P 500 on track for a third consecutive quarter of earnings growth above 25%, backed by near-record margins and broad-based revenue expansion. Surging forward earnings estimates have outpaced index price gains in 2026, resulting in a P/E valuation de-rating.
Beneath the surface, however, profit leadership is shifting. Mega-cap earnings momentum is slipping against lofty expectations, leaving the "Magnificent Seven" trailing the broader index. This leaves markets in a delicate balancing act. With cash and short-duration bonds yielding around 5%, the opportunity cost of equities has risen. Amid elevated rates and geopolitical uncertainty, fading mega-cap dominance could test market resilience – reinforcing the need to broaden exposure across sectors and regions.
Market Spotlight
More than the parts
Traditional portfolios can suffer from an illusion of diversification. Managed in isolated silos, they often double up on the same underlying risks, only discovering the overlap when markets sell off together.
Rather than viewing investments through isolated labels, a Total Portfolio Approach (TPA) aims to balance four core macro forces driving returns: economic growth, duration (interest rate sensitivity), inflation and defensive resilience.
Because stocks, credit, and private equity all rely on economic growth, while government and corporate bonds share duration risk, traditional portfolios are often lopsided, leaving them short of inflation and crisis protection. Under a "one portfolio, one purpose" mindset, teams break down walls to plug those gaps, making room for inflation hedges like commodities and crisis buffers like gold and defensive hedge funds.
Rather than a disruptive overhaul, TPA could be considered as a pragmatic evolution, combining specialist building blocks with agile, factor-aware decisions for stronger long-term returns.
The value of investments and any income from them can go down as well as up and investors may not get back the amount originally invested. The level of yield is not guaranteed and may rise or fall in the future. Past performance does not predict future returns. For informational purposes only and should not be construed as a recommendation to invest in the specific company, country, product, strategy, sector, or security. Diversification does not ensure a profit or protect against loss. Any views expressed were held at the time of preparation and are subject to change without notice. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Source: HSBC Asset Management, Factset, Bloomberg, Macrobond. Data as at 7.30am UK time 06 November 2026.
Lens on…
Beyond the blue wave
A "blue wave" has swept Washington, with Democrats flipping both Houses of Congress. Historically, the year following midterms is the strongest of the presidential cycle for US stocks. In theory, passing the vote lifts election uncertainty, and when the result produces divided government, the gridlock further reduces policy risk by blocking major legislative shifts. Yet investors face choppy waters: without a 2027 budget, a mid-December shutdown looms, the economy is still absorbing a big energy shock, and questions surround AI regulation. Broad stock markets have been consolidating since mid-year, but powerful churn is building beneath the surface. Rapid profit tailwinds are cooling, interest rate headwinds are intensifying, and AI spillovers are reshaping market leadership. Investors will need to get used to a "rolling rotation" between sectors and countries – moving beyond Technology to include value and defensive stocks. |
Shifting tides also reach the dollar. Roughly 15% above its long-run real average, the greenback rode the tech trade; if tech cools and the Fed underdelivers on 2027 rate hikes, the "dollar down" theme might return.
No longer catching a cold
An old adage holds that when global markets sneeze, emerging markets (EM) catch a cold. By that logic, EM local-currency bonds should be reeling. Since mid-August, they have faced a barrage of shocks: elevated oil prices amid Middle East tensions, an AI-led global equity sell-off, and a hawkish repricing of US interest rates. Adding to the pressure, fiscal jitters have rattled Brazil, one of the largest EM debt markets. However, the JPMorgan GBI-EM Global Diversified Index has edged only modestly lower since its August peak, staying roughly flat over the past six months. Since 2024, some EM local bonds have eked out slight average gains during global equity sell-offs, while currency drops have softened. |
Crucially, Brazil's fiscal fever hasn't triggered indiscriminate selling across peers. This resilience lets investors look past isolated country flare-ups.
No place like home
After years chasing returns abroad, Japanese capital is flocking back to native shores. With domestic yields at multi-decade highs, local institutions are stepping in to absorb supply, offering a counterweight as the Bank of Japan shrinks its bond portfolio. This homecoming is gathering momentum. Domestic investors bought a net ¥18.8 trillion of Japanese government bonds (JGBs) during April–September, their strongest first-half spree in 17 years, with pension-backed trust banks accounting for nearly half of those purchases. October’s 20-year auction also drew record demand, with bids nearly six times the competitive allocation. Fiscal risk in France, where Japanese investors hold an estimated ¥23 trillion in bonds, could spur further repatriation. |
Yet what makes sense for yen-based institutions looks less compelling for global portfolios. Locals can now match long-term liabilities at home while avoiding steep FX-hedging costs on foreign debt. For global investors, however, JGB yields still lag those in other major markets, offering scant cushion against a poor fiscal trajectory and the risk of an inflation overshoot.
Past performance does not predict future returns. The level of yield is not guaranteed and may rise or fall in the future. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector, or security. Diversification does not ensure a profit or protect against loss. Any views expressed were held at the time of preparation and are subject to change without notice. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. Source: HSBC Asset Management. Macrobond, Bloomberg, Refinitiv, FactSet. Data as at 7.30am UK time 06 November 2026.
Key Events and Data Releases
Last week

This week

For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector or security. Any views expressed were held at the time of preparation and are subject to change without notice. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Source: HSBC Asset Management. Data as at 7.30am UK time 06 November 2026.
Market review
Global equities were mixed amid market and sector rotations, with semiconductor and AI-related shares weakening noticeably after the Democrats secured a clean sweep in the US midterm elections. In the US, the S&P 500 and Nasdaq fell, while the Philadelphia Semiconductor Index recorded mid-teen percentage losses amid growing concerns over AI regulation. Meanwhile, the Euro Stoxx 50 advanced, led by gains in banking stocks. Asian bourses delivered a mixed performance. Liquidity-support measures from the regulators revived policy optimism and lifted Chinese equities, while Indian equities led regional gains on the back of lower oil prices. However, semiconductor-heavy markets, such as the Kospi, declined notably. In fixed income, US Treasury yields fell as inflation concerns eased. The dollar index was broadly stable, although the US dollar diverged against its major peers. Gold prices rose, while copper prices fell.
Share

Related Insights


Disclaimer
This document or video is prepared by The Hongkong and Shanghai Banking Corporation Limited (‘HBAP’), 1 Queen’s Road Central, Hong Kong. HBAP is incorporated in Hong Kong and is part of the HSBC Group. This document or video is distributed and/or made available by HSBC Bank (China) Company Limited, HSBC Bank (Singapore) Limited, HSBC Bank Middle East Limited (UAE), HSBC UK Bank Plc, HSBC Bank Malaysia Berhad (198401015221 (127776-V))/HSBC Amanah Malaysia Berhad (20080100642 1 (807705-X)), HSBC Bank (Taiwan) Limited, HSBC Bank plc, Jersey Branch, HSBC Bank plc, Guernsey Branch, HSBC Bank plc in the Isle of Man, HSBC Continental Europe, Greece, The Hongkong and Shanghai Banking Corporation Limited, India (HSBC India), HSBC Bank (Vietnam) Limited, PT Bank HSBC Indonesia (HBID), HSBC Bank (Uruguay) S.A. (HSBC Uruguay is authorised and oversought by Banco Central del Uruguay), The Hongkong and Shanghai Banking Corporation Limited – Philippine Branch, HSBC Investment and Insurance Brokerage, Philippines Inc, HSBC Insurance Brokerage Company Limited, HSBC Mexico, S.A. Multiple Banking Institution HSBC Financial Group (collectively, the “Distributors”) and HSBC Bank Middle East Limited Qatar Branch, P.O. Box 57, Doha, Qatar (regulated by Qatar Central Bank for the purpose of this promotion and lead regulated by the Dubai Financial Services Authority) to their respective clients. This document or video is for general circulation and information purposes only.
The contents of this document or video may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose. This document or video must not be distributed in any jurisdiction where its distribution is unlawful. All non-authorised reproduction or use of this document or video will be the responsibility of the user and may lead to legal proceedings. The material contained in this document or video is for general information purposes only and does not constitute investment research or advice or a recommendation to buy or sell investments. Some of the statements contained in this document or video may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors. HBAP and the Distributors do not undertake any obligation to update the forward-looking statements contained herein, or to update the reasons why actual results could differ from those projected in the forward-looking statements. This document or video has no contractual value and is not by any means intended as a solicitation, nor a recommendation for the purchase or sale of any financial instrument in any jurisdiction in which such an offer is not lawful. The views and opinions expressed are based on the HSBC Global Investment Committee at the time of preparation and are subject to change at any time. These views may not necessarily indicate HSBC Asset Management‘s current portfolios’ composition. Individual portfolios managed by HSBC Asset Management primarily reflect individual clients’ objectives, risk preferences, time horizon, and market liquidity.
The value of investments and the income from them can go down as well as up and investors may not get back the amount originally invested. Past performance contained in this document or video is not a reliable indicator of future performance whilst any forecasts, projections and simulations contained herein should not be relied upon as an indication of future results. Where overseas investments are held the rate of currency exchange may cause the value of such investments to go down as well as up. Investments in emerging markets are by their nature higher risk and potentially more volatile than those inherent in some established markets. Economies in emerging markets generally are heavily dependent upon international trade and, accordingly, have been and may continue to be affected adversely by trade barriers, exchange controls, managed adjustments in relative currency values and other protectionist measures imposed or negotiated by the countries with which they trade. These economies also have been and may continue to be affected adversely by economic conditions in the countries in which they trade. Investments are subject to market risks, read all investment related documents carefully.
This document or video provides a high-level overview of the recent economic environment and has been prepared for information purposes only. The views presented are those of HBAP and are based on HBAP’s global views and may not necessarily align with the Distributors’ local views. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination. It is not intended to provide and should not be relied on for accounting, legal or tax advice. Before you make any investment decision, you may wish to consult an independent financial adviser. In the event that you choose not to seek advice from a financial adviser, you should carefully consider whether the investment product is suitable for you. You are advised to obtain appropriate professional advice where necessary.
The accuracy and/or completeness of any third-party information obtained from sources which we believe to be reliable might have not been independently verified, hence customers must seek several sources prior to making investment decisions.
The following statement is only applicable to HSBC Mexico, S.A. Multiple Banking Institution HSBC Financial Group with regard to how the publication is distributed to its customers: This publication is distributed by Wealth Insights of HSBC México, and its objective is for informational purposes only and should not be interpreted as an offer or invitation to buy or sell any security related to financial instruments, investments or other financial product. This communication is not intended to contain an exhaustive description of the considerations that may be important in making a decision to make any change and/or modification to any product, and what is contained or reflected in this report does not constitute, and is not intended to constitute, nor should it be construed as advice, investment advice or a recommendation, offer or solicitation to buy or sell any service, product, security, merchandise, currency or any other asset.
Receiving parties should not consider this document as a substitute for their own judgment. The past performance of the securities or financial instruments mentioned herein is not necessarily indicative of future results. All information, as well as prices indicated, are subject to change without prior notice; Wealth Insights of HSBC Mexico is not obliged to update or keep it current or to give any notification in the event that the information presented here undergoes any update or change. The securities and investment products described herein may not be suitable for sale in all jurisdictions or may not be suitable for some categories of investors.
The information contained in this communication is derived from a variety of sources deemed reliable; however, its accuracy or completeness cannot be guaranteed. HSBC México will not be responsible for any loss or damage of any kind that may arise from transmission errors, inaccuracies, omissions, changes in market factors or conditions, or any other circumstance beyond the control of HSBC. Different HSBC legal entities may carry out distribution of Wealth Insights internationally in accordance with local regulatory requirements.
Important Information about the Hongkong and Shanghai Banking Corporation Limited, India (“HSBC India”): HSBC India is a branch of The Hongkong and Shanghai Banking Corporation Limited. HSBC India does not distribute or refer investment products to those persons who are either the citizens or residents of United States of America (USA), Canada or any other jurisdiction where such distribution or referral would be contrary to law or regulation.
HSBC India is an AMFI-registered Mutual Fund Distributor and an AMFI-registered Specialized Investment Fund (SIF) Distributor. HSBC India distributes select mutual fund schemes and SIF strategies of empaneled Asset Management Companies, and acts as a referrer of other third-party investment products. Mutual Fund investments are subject to market risks, read all scheme-related documents carefully. AMFI-registered Mutual Fund Distributor | Date of Initial Registration: 19 Feb 2002 | ARN-0022 I Validity of ARN: 18 Feb 2027. AMFI-registered SIF Distributor I Date of initial registration: 27 Oct 2025 | ARN-0022 I Validity of ARN: 26 Oct 2028.
HSBC India will receive commission from HSBC Asset Management (India) Private Limited, in its capacity as a AMFI registered mutual fund distributor of HSBC Mutual Fund. The Sponsor of HSBC Mutual Fund is HSBC Securities and Capital Markets (India) Private Limited (HSCI), a member of the HSBC Group. Please note that HSBC India and the Sponsor being part of the HSBC Group, may give rise to real, perceived, or potential conflicts of interest. HSBC India has a policy in place to identify, prevent and manage such conflict of interest. For more information related to investments in the securities market, please visit the SEBI Investor Website: https://investor.sebi.gov.in/ and the SEBI Saa₹thi Mobile App.
The following statement is only applicable to HSBC Bank (Taiwan) Limited with regard to how the publication is distributed to its customers: HSBC Bank (Taiwan) Limited (“the Bank”) shall fulfill the fiduciary duty act as a reasonable person once in exercising offering/conducting ordinary care in offering trust services/ business. However, the Bank disclaims any guarantee on the management or operation performance of the trust business.
The following statement is only applicable to PT Bank HSBC Indonesia (“HBID”): HBID is licensed and supervised by Indonesia Financial Services Authority (“OJK”). Investment products that are offered in HBID are third party products, HBID is a selling agent for third party products such as Mutual Funds and Bonds. HBID and HSBC Group (HSBC Holdings Plc and its subsidiaries and associates company or any of its branches) do not guarantee the underlying investment, principal or return on customer’s investment. You must read and understand the investment policy of each investment product to see if a product contains ESG and sustainability elements and is classified as an ESG and sustainable investment. Investment in Mutual Funds and Bonds are not covered by the deposit insurance program of the Indonesian Deposit Insurance Corporation (“LPS”).
Important information on ESG and sustainable investing
Today we finance a number of industries that significantly contribute to greenhouse gas emissions. We have a strategy to help our customers to reduce their emissions and to reduce our own. For more information visit www.hsbc.com/sustainability.
In broad terms “ESG and sustainable investing” products include investment approaches or instruments which consider environmental, social, governance and/or other sustainability factors to varying degrees. Certain instruments we classify as sustainable may be in the process of changing to deliver sustainability outcomes. There is no guarantee that ESG and Sustainable investing products will produce returns similar to those which don’t consider these factors. ESG and Sustainable investing products may diverge from traditional market benchmarks. In addition, there is no standard definition of, or measurement criteria for, ESG and Sustainable investing or the impact of ESG and Sustainable investing products. ESG and Sustainable investing and related impact measurement criteria are (a) highly subjective and (b) may vary significantly across and within sectors.
HSBC may rely on measurement criteria devised and reported by third party providers or issuers. HSBC does not always conduct its own specific due diligence in relation to measurement criteria. There is no guarantee: (a) that the nature of the ESG / sustainability impact or measurement criteria of an investment will be aligned with any particular investor’s sustainability goals; or (b) that the stated level or target level of ESG / sustainability impact will be achieved. ESG and Sustainable investing is an evolving area and new regulations are being developed which will affect how investments can be categorised or labelled. An investment which is considered to fulfil sustainable criteria today may not meet those criteria at some point in the future.
THE CONTENTS OF THIS DOCUMENT OR VIDEO HAVE NOT BEEN REVIEWED BY ANY REGULATORY AUTHORITY IN HONG KONG OR ANY OTHER JURISDICTION. YOU ARE ADVISED TO EXERCISE CAUTION IN RELATION TO THE INVESTMENT AND THIS DOCUMENT OR VIDEO. IF YOU ARE IN DOUBT ABOUT ANY OF THE CONTENTS OF THIS DOCUMENT OR VIDEO, YOU SHOULD OBTAIN INDEPENDENT PROFESSIONAL ADVICE.
© Copyright 2026. The Hongkong and Shanghai Banking Corporation Limited, ALL RIGHTS RESERVED.
No part of this document or video may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording or otherwise, without the prior written permission of The Hongkong and Shanghai Banking Corporation Limited.